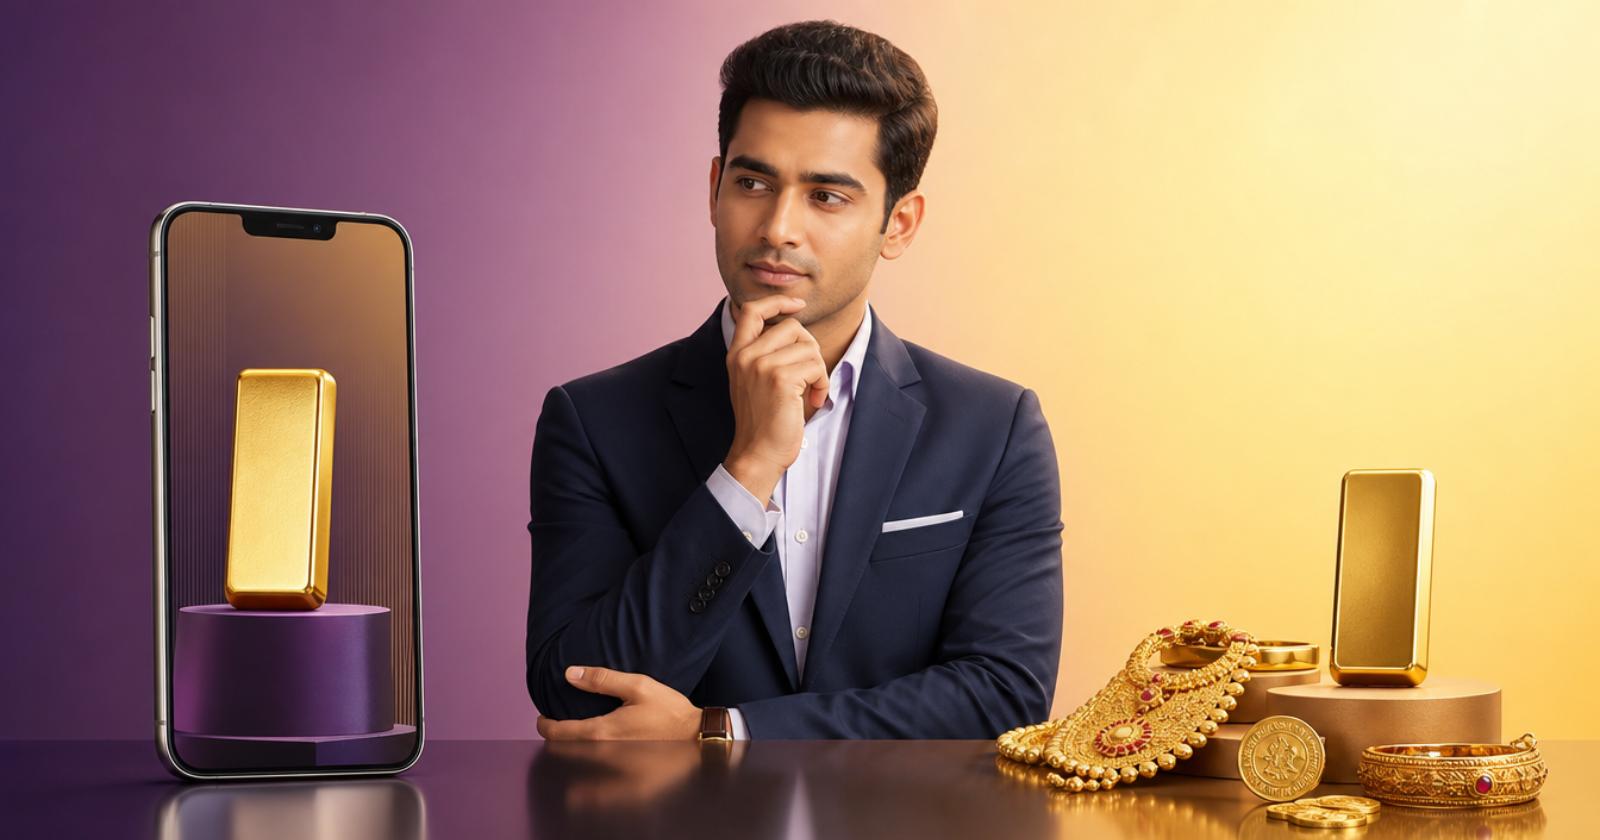
There's a moment almost every gold buyer in India reaches eventually, standing between a jewellery store counter and a phone screen, wondering which version of gold actually makes more sense for what they're trying to do. Physical gold has centuries of trust behind it. Digital gold has convenience most people didn't know they needed until they tried it. Neither is wrong. The right answer depends entirely on what the gold is for.
Why Gen Z Indians Are Choosing Digital Gold?
A shift has been happening among new age investors over the past few years. Investment trends increasingly show young earners buying gold the same way they buy anything else, through an app, in small amounts, without ever visiting a jewellery store. For financial planning for Gen Z, this makes practical sense: most young investors don't have a locker, aren't ready to store valuables at home, and would rather put ₹200 into gold on a random Tuesday than wait to save up for a full coin.
This is really why young investors in India have taken to digital gold so naturally. It's easy to enter, genuinely beginner-friendly, since you can start with a lower amount and gradually increase it as income grows, which also makes it a practical fit for salaried professionals easing into gold rather than committing a large sum upfront. It fits into modern investment options the same way SIPs and UPI-linked savings do: low commitment, instant access, and no physical hassle. It's less a rejection of traditional gold and more an adaptation of it to how a younger generation already manages money.
You May Also Like: Gold vs Nifty: Which Performed Better in the Last 10 Years?
How to Buy Digital Gold, and What to Expect?
Learning how to buy digital gold takes minutes. Most banking apps, payment apps, and dedicated gold platforms let you buy digital gold online with small amounts, instantly crediting the equivalent grams to your account, backed by certified 24K gold held in an insured vault. There's no making charge, no storage worry, and the digital gold price updates in real time, matching the market rate.
The best way to invest in digital gold, for most people, isn't a single large purchase; it's small, regular buying, similar to a mutual fund SIP, letting the holding build gradually over months or years without needing to time the market.
The Difference Between Digital Gold and Physical Gold
The core difference between digital gold and physical gold lies in their form and purpose. Digital gold is standardised as 24-karat gold, while physical gold can vary in purity. Physical gold, especially jewellery, also carries emotional and cultural value that digital gold can’t replicate; it's meant to be worn, gifted, or passed down.
Digital gold, on the other hand, is built for flexibility, easy to buy, sell, or convert, with none of the storage or security concerns that come with physical possession.
Physical gold leasing adds another layer worth knowing about here. For gold that's sitting idle, old jewellery or coins nobody wears, leasing allows that gold to be put to use within the jewellery trade while ownership stays entirely intact, earning additional gold weight than sitting completely passive. It's a middle path that doesn't require choosing between physical gold's sentimental value and digital gold's flexibility.
You May Also Like: How Digital Gold Works And What Are The Advantages For Indians
Is Digital Gold Taxable?
The answer to Is digital gold taxable? is yes. Digital gold is taxed similarly to physical gold. Every purchase attracts 3% GST upfront. On selling, if the gold is held for less than 24 months, the profit is added to your income and taxed at your applicable slab rate. If held beyond 24 months, it qualifies for long-term capital gains, currently taxed at a flat 12.5% without indexation benefit. Knowing how to sell digital gold and when it matters, since crossing the 24-month mark can meaningfully change the tax outcome on the same profit. Tax rules can change, so it’s always advisable to consult a qualified CA for clarity based on your individual circumstances.
For someone considering both forms of gold, myGold supports digital gold purchases and SIPs, while physical gold leasing offers existing physical-gold owners a way to put eligible jewellery or coins to use rather than leaving them idle, with the potential to grow their gold weight by up to 5% through leasing. This creates a practical way to approach digital and physical gold based on their different purposes, without treating them as interchangeable investments.
Conclusion
Digital gold and physical gold aren't really competing products; they're two different ways of holding the same underlying asset, each suited to a different purpose. This is especially relevant to Gen Z investment trends, where convenience, digital access, and flexible investing options increasingly shape how younger investors approach traditional assets. For young, new-age investors building a habit, digital gold offers an easy entry point. For gold meant to be worn or passed down, physical gold still holds a place nothing digital can replace. And for gold sitting idle in either form, leasing offers a way to let it do a little more, without asking anyone to choose sides.
FAQs
1. Do you pay tax on digital gold?
Yes, 3% GST on purchase, and capital gains tax on profit when sold, based on the holding period.
2. Why do Gen Z investors prefer digital gold SIPs?
Low entry amounts, no storage hassle, and app-based convenience that fits how they already manage money.
3. How do I choose between digital gold and physical gold?
Base it on purpose: physical for wearing or gifting, digital for flexibility, ease of buying, and eventual selling.
4. Is selling digital gold taxable income?
Yes, profits are taxed as capital gains at slab rates within 24 months, or at a flat 12.5% beyond that.